Upgrade

Screenshots
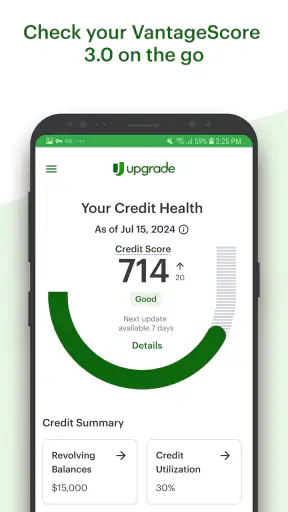
Details
- Rating
- 3.80K reviews
- Version
- 1.33.0
- Developer
- Upgrade, Inc.
Analysis by Norviv
Choosing a finance app is less about finding the one with the longest feature list and more about finding a service that matches the way you actually manage money. I approached Upgrade with that in mind because it brings personal loans, cards, and rewards checking into one place rather than focusing on only one financial task. After spending time with the app, I found it most interesting as a central starting point for people who want borrowing and everyday spending tools connected in the same account.
That combination is also the reason I would not recommend it automatically to everyone. A person who only wants a simple checking account may prefer a dedicated banking app, while someone comparing loans carefully may want a lender-focused service with a broader comparison process. Upgrade makes more sense when you value convenience across several financial products and are willing to read the terms of each product before committing.
How I Decided Whether Upgrade Fits
My first test was practical: could I understand what role the app would play in my financial routine? Upgrade, Inc. develops the app, which is free to download and aimed at everyone from an age-rating perspective. Its finance category is broad, but the useful question is whether its three main areas—personal loans, cards, and rewards checking—solve a connected problem for you.
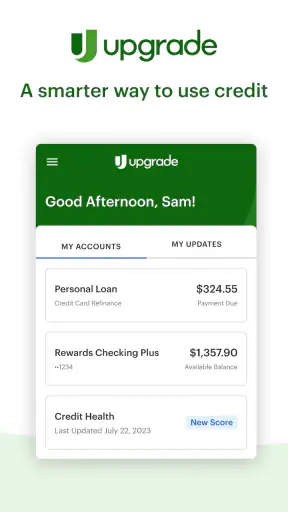
I would begin by asking how often I need to move between borrowing, spending, and monitoring account activity. If those tasks already happen in separate places, bringing them together can reduce the number of apps and logins I use. That is a real convenience, especially when I am checking whether a planned purchase fits alongside an existing repayment obligation.
My second criterion was clarity. Finance apps can look polished while still making important decisions feel rushed. With Upgrade, I would take time to distinguish between exploring an option and actually accepting a financial product. A clean interface is helpful, but it does not replace reading repayment details, card conditions, or account terms. The app is best treated as a tool for managing choices, not as a reason to make them quickly.
The third criterion was flexibility. A combined financial app can be efficient, but it may also encourage users to keep everything with one provider. That is convenient until another service offers a better fit for a particular need. I therefore judged Upgrade not only by how well its products work together, but also by whether it remains useful when I choose to keep some financial products elsewhere.
There is a practical workflow I found especially sensible. I would use the app to review my day-to-day balance and card activity first, then consider borrowing only after looking at the effect on my regular budget. This order matters. Starting with a loan offer and trying to build a budget around it can make a large purchase feel more affordable than it really is. Starting with ordinary cash flow keeps the decision grounded.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
Upgrade has attracted a substantial audience: it has more than a million installs, an average rating of 4.4 from around thirty thousand ratings, and roughly four thousand written reviews. Those figures suggest that the app is not a niche experiment, but they do not tell me whether it is right for a particular financial situation. The important takeaway is that users should still evaluate the actual product terms and their own habits.
What the combined approach feels like in everyday use
Imagine I need to replace a broken household appliance while also trying to keep monthly spending predictable. In a fragmented setup, I might check one app for my checking balance, another for card activity, and a separate website for a loan inquiry. Upgrade’s appeal is that I can begin that review in one financial environment. I can see whether the purchase belongs in my normal spending plan, consider the card as a payment tool, and investigate a personal loan without immediately treating borrowing as the answer.
That workflow is more useful than simply having several product names on one screen. It encourages a pause between identifying a need and choosing a way to pay for it. I would still compare the total repayment cost and the effect on my future budget, but the app can make the first review less scattered.
Where the app wins for connected money tasks
The strongest part of Upgrade is its breadth. Many finance apps specialize in one job: a checking account for deposits and bills, a card app for transactions, or a loan marketplace for borrowing. Upgrade instead presents a connected set of financial tools. For me, that reduces mental switching when I am trying to understand how spending and borrowing interact.
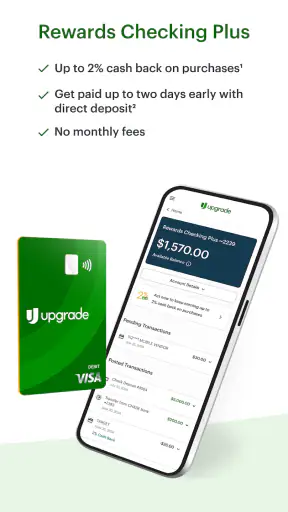
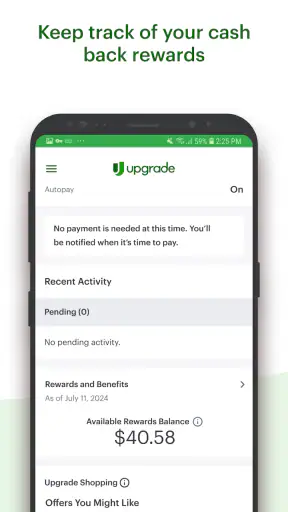
The rewards checking element is also relevant for people who use one account as a daily money hub. If I want to monitor ordinary account activity while also considering card use, keeping those tasks close together can make routine reviews easier. I would not choose it solely because the word “rewards” sounds attractive; I would first check how the account’s conditions fit my own use. Still, having that option alongside the other products gives the app a wider role than a loan-only service.
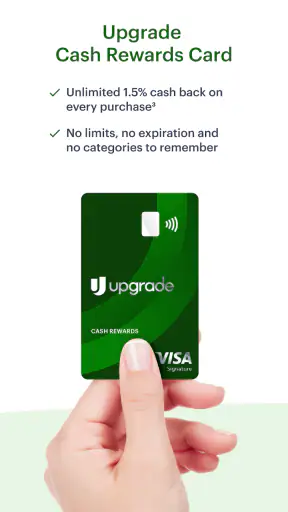
The card can be useful for someone who wants a dedicated way to organize purchases while keeping an eye on the rest of their finances. One non-obvious advantage of a combined app is the ability to review a purchase in context. Instead of asking only whether I have enough available credit, I can ask whether the purchase works with my checking balance and any repayment commitments. That broader question is healthier than treating each financial product as an isolated pocket of money.
I also like the possibility of using the app in stages. I do not have to treat every feature as a package. A person may begin by exploring the account experience, later look at the card, and only investigate a loan when a genuine need appears. That staged approach helps prevent the common mistake of adopting a financial product simply because it is presented next to another one.
Another strength is accessibility for people who dislike managing several separate services. The app is available on newer mobile operating systems, with a minimum requirement of version 12, so it is designed for users with relatively current devices. The current app version is 1.33.0. In my view, that makes it important to keep the phone’s operating system updated enough to remain compatible rather than assuming every older device will work.
Small habits that make the app more useful
I would use Upgrade with a weekly review rather than opening it only when money feels tight. A short check of account activity, card spending, and upcoming obligations can reveal patterns earlier. The benefit is not a special feature; it is the way the app’s connected structure supports a repeatable routine.
I would also separate “available” from “affordable” in my own notes. A card may make a purchase possible today, but that does not mean the payment belongs in my budget. Likewise, a personal loan may spread a cost over time, but the new obligation still competes with rent, utilities, savings, and ordinary spending. Upgrade can place these choices near each other, but I remain responsible for making the comparison.
A third useful habit is to enter the app with a specific question. For example, I might ask, “Can my normal cash flow handle this purchase?” rather than browsing every offer. This reduces the temptation to interpret product availability as a recommendation. It also makes the app feel more like a financial workspace and less like a stream of prompts.
Where an alternative may be a better fit
Upgrade is not automatically the best choice for someone who wants a bare-bones checking experience. If I only need a place for everyday deposits, bill payments, and basic balance checks, a dedicated checking provider may feel simpler because it does not place lending and card decisions in the same environment. The advantage of fewer choices can be valuable when simplicity is the main goal.
A loan-focused alternative may suit a borrower who wants to compare several lenders or concentrate exclusively on repayment terms. Upgrade’s integrated approach is convenient, but convenience should not replace comparison. If the loan is the only reason I am downloading the app, I would look at the full cost, repayment schedule, and eligibility requirements before deciding whether a broader financial app adds anything for me.
There is also a case for keeping spending and borrowing separate. Some people find it easier to control debt when their card activity and loan management are not presented alongside everyday account features. If seeing multiple financial options encourages me to spend or borrow more often, a less expansive service would be the wiser choice, even if it means using more than one app.
Users who already have a trusted bank, card, and budgeting system may gain little from switching everything to one place. In that situation, Upgrade would need to offer a clear practical improvement, such as reducing the effort of monitoring connected products. If it merely duplicates tools I already understand, the change may create more work than value.
I would also avoid choosing it on the assumption that one provider must be best across all three areas. A rewards checking account, a card, and a personal loan each deserve separate scrutiny. The fact that they appear within one app is useful, but it does not make their terms interchangeable. This is the main trade-off of the all-in-one design: less friction between products, but a greater need for disciplined comparison.
The real cost of switching
Downloading a free app is the easy part of changing financial services. The harder cost is reorganizing habits. If I move routine money management into Upgrade, I need to decide which payments, transfers, and spending checks belong there. I also need to preserve access to existing records and make sure I do not overlook an obligation that still runs through another provider.
I would switch gradually rather than moving everything on the first day. First, I would explore the interface and understand where account activity, card information, and loan details appear. Then I would use it for observation before changing important routines. This gives me time to learn whether the app’s organization actually suits me.
For a card user, the transition also involves changing the way purchases are reviewed. I would not close an existing card simply because Upgrade offers another option. I would compare the practical role of each card, check recurring payments, and avoid creating duplicate spending channels that make my budget harder to follow. The same caution applies to checking: moving money without planning can interrupt bills or scheduled transfers.
Borrowing requires even more patience. If I am considering a personal loan, I would treat the application process as a separate decision from downloading the app. I would prepare a clear reason for the loan, calculate a payment I can sustain, and read the terms before accepting anything. The app may make the process convenient, but the financial commitment remains long after the initial screen disappears.
Privacy and security habits are part of the switching cost too. I would use a strong device passcode, keep the app and operating system current, and avoid reviewing sensitive financial information on an unsecured public connection. These are ordinary precautions, but they matter more when one app brings several parts of my financial life together.
The age rating of Everyone makes the app broadly approachable, but that should not be confused with financial suitability for every person. Younger users and anyone new to credit may need extra help understanding repayment, card use, and account terms. I would encourage a first-time borrower to discuss the decision with a trusted, financially knowledgeable person rather than relying on an app interface alone.
Who I would recommend it to
I would recommend Upgrade to someone who wants a single mobile starting point for personal loans, card activity, and rewards checking, especially if those needs overlap in daily life. It is a good candidate for a person who values a unified view and is comfortable taking responsibility for comparing each product on its own terms.
It may also suit someone who is tired of jumping between separate financial services. The app’s value grows when the user actually benefits from the connection: checking spending before considering borrowing, reviewing card activity alongside account balances, or using a regular weekly money check to keep decisions organized.
I would be more cautious about recommending it to someone who wants only one narrow service, dislikes seeing borrowing options near everyday spending, or already has a well-organized setup that works. In those cases, a specialist alternative may be clearer and easier to control. The best choice is not the app with the most categories; it is the one that supports good decisions without adding temptation or confusion.
My final view is favorable but measured. Upgrade works best as a connected finance workspace, not as a shortcut around careful financial judgment. Its free access, broad product focus, and established presence make it worth exploring for the right user. I appreciate that it can bring ordinary spending and larger borrowing decisions into one review, because that is how those choices affect real life.
Before switching, I would start with one purpose, read the relevant terms, and keep existing arrangements in place until the new workflow proves reliable. If I wanted a unified way to examine my financial choices, I would give Upgrade a serious look. If I wanted only a simple account or the widest possible loan comparison, I would choose a more focused alternative instead.
Overall, Upgrade earns its place on my shortlist because it connects several common money tasks without requiring me to treat them as one decision. That distinction is important. Used deliberately, it can make financial organization easier; used casually, its convenience could encourage choices that deserve more thought.
Frequently Asked Questions
01What is Upgrade, and what can I use it for?
Upgrade is a financial app designed to help users manage borrowing, spending, and everyday money services in one place. Depending on your eligibility and location, it may provide access to personal loans, a credit card, checking features, budgeting tools, and credit-building options. Available products can vary, so review the current terms carefully before applying.
02Does Upgrade check my credit score when I apply?
Yes, Upgrade may review your credit information when you request certain products, such as a personal loan or credit card. In some cases, checking available offers may begin with a soft credit inquiry that does not affect your score, while submitting a formal application can result in a hard inquiry. The app should explain which type applies before you continue.
03Are Upgrade loans or credit products guaranteed to be approved?
No. Approval is not guaranteed, and Upgrade evaluates applications using information such as your credit history, income, debt, identity, and other eligibility requirements. Even if you receive an offer, the interest rate, loan amount, repayment period, fees, and final terms may differ according to your financial profile. Read the complete agreement before accepting.
04What fees and interest charges should I expect with Upgrade?
Costs depend on the specific Upgrade product you choose and the terms you are offered. Personal loans may include interest and, in some cases, an origination fee that is deducted from the loan proceeds. Credit products can also have interest charges, late-payment consequences, or other costs. Always check the APR, total repayment amount, fees, and payment schedule in the offer details.
05Is Upgrade safe to use, and how does it protect my information?
Upgrade uses standard security measures intended to protect account information and financial data, including encrypted connections and identity-verification procedures. However, no online service can eliminate every security risk. Use the official app, create a strong unique password, enable available security features, and avoid sharing verification codes. Also review permissions and the privacy policy before submitting sensitive information.


